Bullstory Research June 16, 2026
K-beauty 3after years 10a scenario of becoming many times larger
Key takeaways
2026years 6As of month, K-beauty has entered a structural growth phase centered on North America, Europe, and Japan, moving away from reliance on China. From a stock-price perspective, the key is large ODMs, global distribution platforms, and a selective mix of large brands. A representative leading name often mentioned is Cosmax(192820).
K-Beauty has 2026moved beyond its dependence on China and entered a structural growth phase centered on North America, Europe, and Japan, and in the stock market the combination of large ODMs + global distribution platforms + selective large brands that supports this from behind the scenes still remains the core strategic axis.
Below, 2026as of 6we will reorganize the outlook changes together with the names with remaining upside in their share prices or those that have established themselves as “leading stocks”.
1. 2026Summary of the K-Beauty industry in one line
Looking at export data by country, the picture for Korean cosmetics is solidifying around continued weakness in China, growth led by the United States and Europe, and expanding shares in Japan and the Middle East.
Especially in the U.S. and Europe, indie brands (such as Beauty of Joseon, Tirtir, and Romand) are expanding the market with short-form marketing based on TikTok and Instagram Reels, along with reasonable pricing, while production is fully handled by Korean ODMs.
2. Export landscape diversification: shrinking share of China, expanding North America, Europe, and Japan
In several reports, it is commonly assessed that the increase in K-beauty exports to the U.S. and Europe more than offsets the weakness in China. In Europe, the share of Korean products is rising rapidly, centered on derma cosmetics and sun care, and some analyses say that in Eastern Europe, including 7 countries such as Russia and Poland, the share of Korean cosmetics exports has increased significantly enough to rival China.
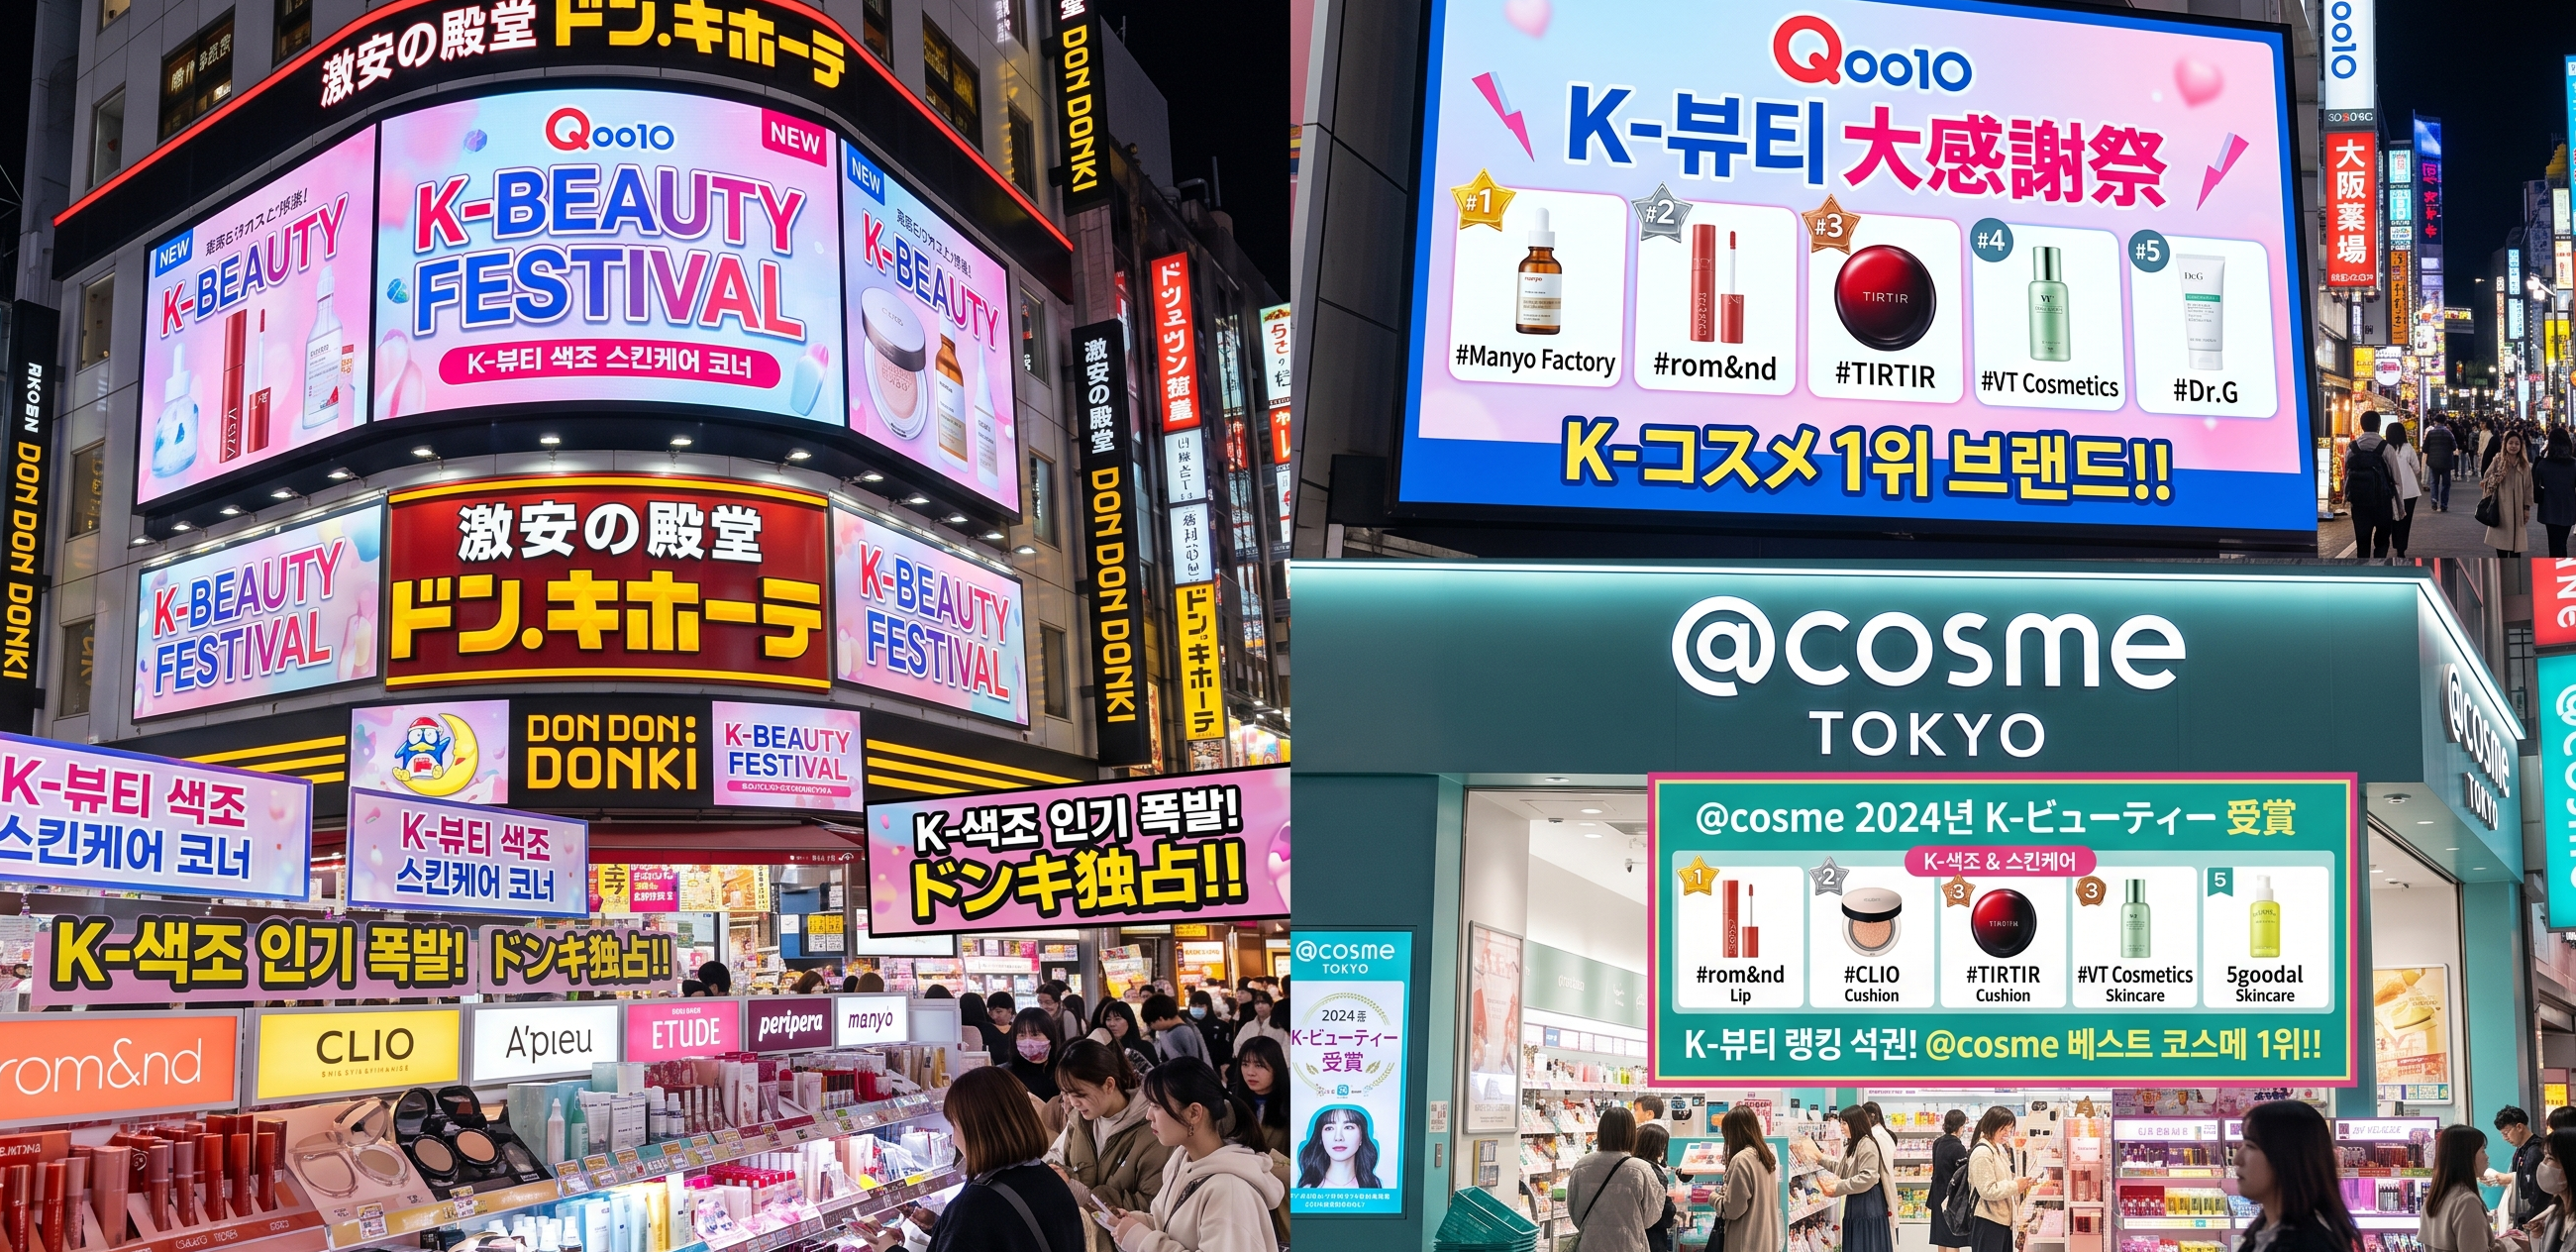
In Japan, 1020the 10generation has dominated channels such as Don Quijote, Qoo
In this process, it has become common for brand companies to use Korean ODMs instead of in-house factories, and for distribution to take a mixed structure of local drugstores + online platforms + K-beauty specialist wholesalers.
3. Shift in power: mega brands → indie brands, and the value chain toward ODMs
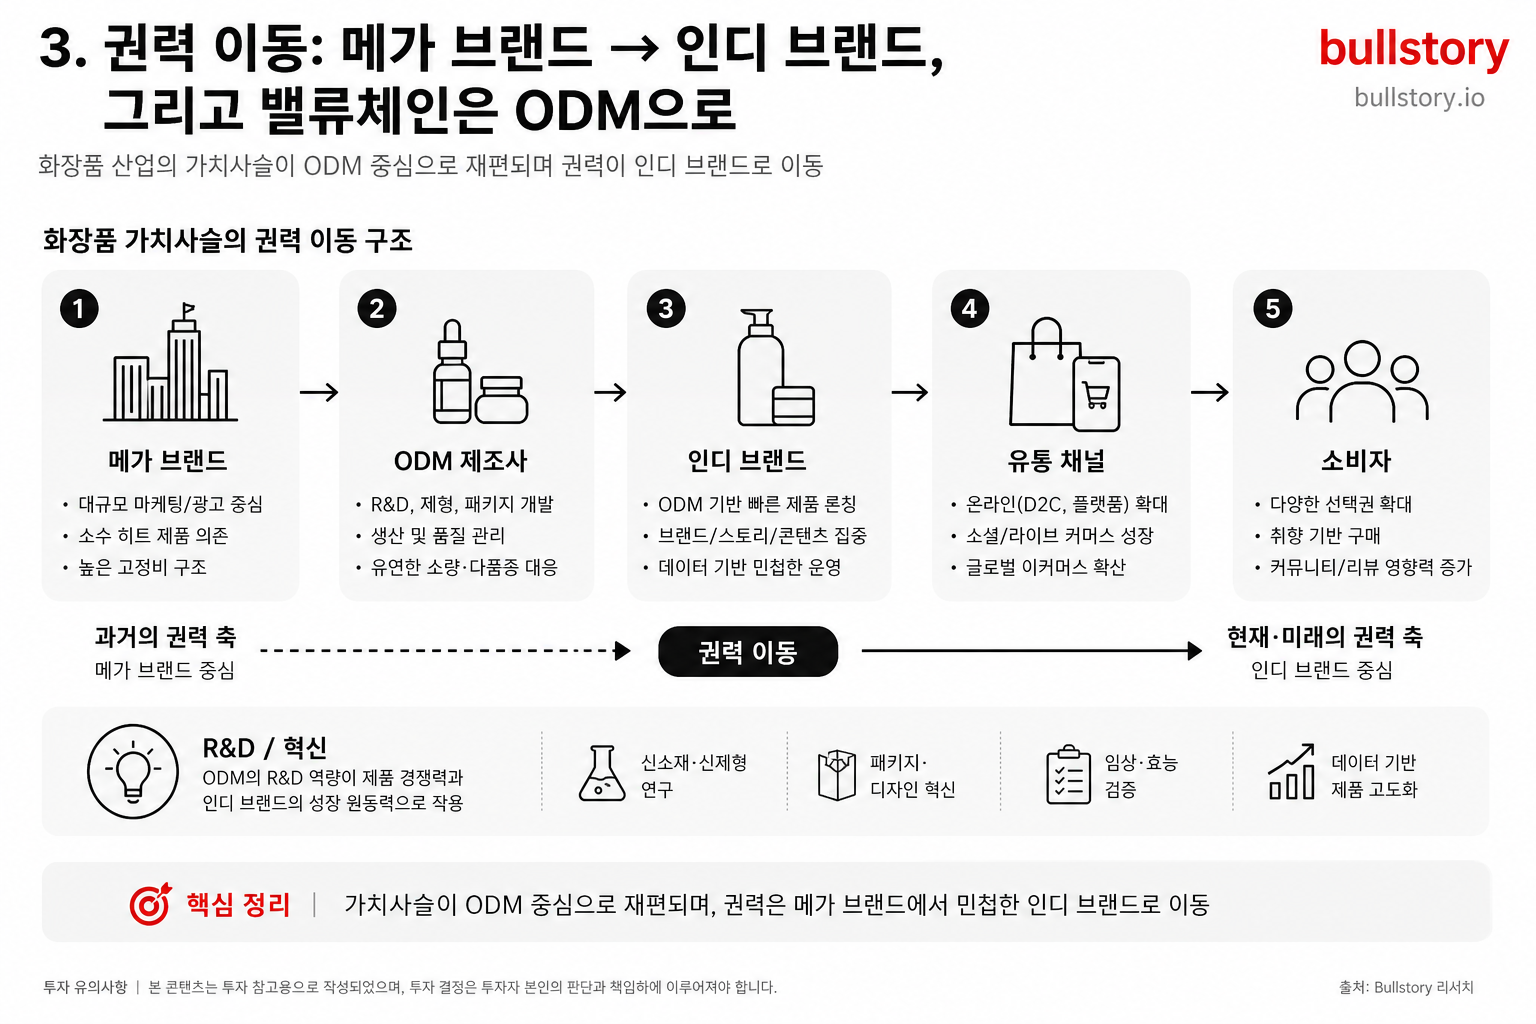
The center of the current cycle is not legacy large brands such as Amorepacific and LG Household & Health Care, but indie brands focused on planning and marketing, and the ODMs and distributors supporting them from behind the scenes.
SK Securities and others view it as new indie brands focusing on planning and SNS marketing without their own production facilities, which will keep increasing their dependence on orders from large domestic ODMs, and they summarize that because indie brand life cycles are short, large ODMs with a diverse customer base are a structural beneficiary.
From the distribution side, moving away from duty-free stores and daigong-centered B2B structure,
-
Amazon and TikTok Shop
-
Olive Young Global Mall
-
K-beauty specialists such as StyleKorean (Silicon Two) B2B/B2platforms
have become established as the main channel through cross-border e-commerce.
These channels are building an agile product development structure that accumulates real-time review and purchase data and feeds it back into planning the next products.
4. Pick & Shovel Strategy: The ‘real leaders’ of this cycle are ODMs and distributors
Taking several house reports and market trends together, in this K-beauty cycle, the axis that shows the most consistent beta and alpha in both stock price and earnings terms is “OEM/ODM + global distribution”785 is.
-
Indie brands have wide swings in hit products and high lifecycle volatility
-
Legacy large brands still face restructuring risk in China and duty-free channels,
-
ODMs and distributors are “an essential gateway that every winning brand must pass through”774which makes them well suited to a Pick & Shovel strategy.
From below, 2026as of 6we briefly summarize the stocks that can be viewed as the industry leader and long-term growth stocks.
5. Cosmax(192820): the ‘industry leader’ in cosmetics ODM
In reports from several brokerages, Cosmax is being presented as a global 1-tier cosmetics ODM and the cosmetics sector’s top pick.
As orders from indie brands and U.S. exports continue to strengthen in non-China regions such as the U.S., Europe, and Southeast Asia, 85s evaluation is that it also recorded double-digit revenue growth and solid operating profit in the 2026-1quarter.
-
Investment points
-
Strong growth in the U.S., Thailand, and Indonesia subsidiaries, while risk in China is being eased through customer diversification.
-
With a large share of indie brands such as Rom&nd, Tirtir, and Anua, the shorter the brand life cycle, the greater the leverage for large ODMs that have a diverse customer base.
-
At Hanwha, Yuanta, and Daol, 20high end~midrange and higher target prices (for example, 24thousand*28.8thousand won level) and buy opinions** are being maintained, so 20there is a sense that meaningful upside still remains at the low-to-mid level of the ten-thousand-won range.
-
Role within the sector
-
In this K-beauty renaissance, the prevailing view is that it is a stock that simultaneously serves as the “ODM leader” + “sector beta play.”
6. Kolmar Korea(161890): a leader in sun care and derma, a preferred ODM pick
Kolmar Korea is an ODM with an unmatched portfolio in sun care and derma cosmetics, and it is consistently noted that a significant share of sunscreen lines from global beauty brands is produced through Kolmar Korea.
According to IR materials, 2026based on that year, strong growth in key sun care orders and the expansion of domestic derma brands have driven sales and profit to trend upward.
-
Investment points
-
With the expanding need for climate-change adaptation and skin-aging prevention, a structural picture emerges: high growth in the global sun care market -> increased orders for Kolmar Korea.
-
Based on its own IR and a FnGuide snapshot, 2026when the share price was being managed around the low 7range at the beginning of the year, securities firms cited target prices in the upper 9range (for example, 96,950won, etc.) and a PER of around 14times, noting additional upside potential.
-
However, profitability at overseas subsidiaries, such as losses at the U.S. factory, is more volatile than at Cosmax, and the report also identifies this as a major risk.
-
Role within the sector
-
If Cosmax is the sector’s top pick and leader, Kolmar Korea is the second-favored ODM with a presence in niche areas such as sun care and derma.
7. Cosmecca Korea(241710): 2the sun ODM leverage play
In a JoongAng Ilbo and Hankyung article, analysis says that the spillover effect is becoming more pronounced as orders are distributed across top-tier ODMs such as Cosmecca Korea and C&C International.3·4.
Kosmeca is seen as having stepped onto a turnaround in performance 2025since the year, thanks to rising orders from North American indie brands and improved profitability at its U.S. subsidiary, Inglewood Lab.
-
Investment Points
-
From Daol, Yuanta, and Hanwha, 9in the high ten-thousand-won range to10offer target prices and buy ratings, and 2025to 2026forecast strong growth in sales and operating profit for the year.
-
In Hankyung consensus as well, it is defined as “a beneficiary of the 2leveraged upturn stage in K-ODM,”로 it emphasizes that the stock can simultaneously benefit from a valuation discount versus leading peers and the spillover effect.
-
Check Points
-
It is necessary to track whether production efficiency and cost-management issues are being structurally improved, and whether the profit contribution of the U.S. subsidiary is steadily increasing.
8. C&C International(352480): an ODM focused on color cosmetics, with only cautious short-term visibility
C&C International is an ODM specializing in color cosmetics such as lip and eyeshadow, and analysis says it is rebuilding orders mainly from North American indie color-cosmetics brands.
However, 2025year-end to 2026year-start, Samsung Securities cited initial inefficiencies in new product launches and production disruptions caused by ERP implementation as reasons to cut its investment opinion from Buy to Neutral and its target price from 5ten-thousand won to 3ten-thousand won, warning that earnings visibility had worsened.
-
Investment points
-
A structure that can receive a large volume leverage effect when the color-cosmetics trend cycle revives and orders from North American indie brands increase.
-
Based on the company disclosure, 2026year-start current price moved in the upper- to middle- of the 3ten-thousand won range, and with the target price lowered to 3ten-thousand won, it signals that there is not much upside in the short-term consensus.
-
Check point
-
Rather than aiming for a full-scale turnaround, it seems appropriate to position it as a risk-taking 2·3stock that is betting on slightly stronger momentum than Cosmax and Cosmecca (the color cosmetics cycle).
9. SILICON 257720: the “artery” of global K-beauty distribution and a leading distributor stock
Silicon operates the Style Korean platform and distributes 400 cosmetics brands from Korea across 100 countries, making it a leading K-beauty cross-border distributor.
News1·Korea Economic Daily and others said that as of the beginning of the year, it was expected to achieve 2026 in sales compared with the previous year, 1and even described it as 5 times sales growth in a few years,10 identifying it as the biggest beneficiary of the K-beauty export boom.
-
Investment point
-
Several brokerages, including Samsung, KB, NH, and Kiwoom, have issued BUY recommendations for SiliconTwo and 6to 6.7won-level target prices (for example: 60,000won·63,000won·65,000won, etc.), while keeping it as the top pick in the sector.
-
According to the article, at certain points there has been repeated analysis that there is additional upside potential of 30to 60% versus the previous day's closing price.
-
It is emphasized that it is benefiting simultaneously from three pillars: a rebound in exports to the United States, an acceleration in exports to Europe, and the start of exports to the Middle East, and it is being evaluated as a player that can supply fragmented K-beauty demand in Europe in an integrated way.3.},
-
Role within the sector
-
In cosmetics distribution, it has established itself as "the leading stock in global K-beauty distribution + the most intuitive growth play"로 and it is repeatedly mentioned that SiliconTwo is effectively an essential partner when indie brands expand overseas.
10. Traditional large brands: Amorepacific·LG Household & Health Care
Amorepacific(090430): Legacy leader + subsidiary COSRX momentum
Amorepacific is still, by sector market capitalization, a leading large-cap cosmetics stock (market leader)로, and is receiving indirect benefits from the global growth of its subsidiary COSRX and the spread of indie brands in North America and Europe.
Several brokerages are 2026year 1in the quarterly review, presenting buy ratings and 17~18a target price in the ten-thousand-won range, 20upside potential in the high-percent range.
Based on DCF, with WACC 9.9%, and a perpetual growth rate 3.6% applied, there is analysis that the target price is 18ten-thousand won, 12forward P/E on a months basis 32times level,
- In other reports, the target price is 17.8KRW ten thousand, 4as of the start of the month the current price is 12around KRW ten thousand, indicating about 39% upside potential.
However, SK Securities, Heungkuk Securities, and others cite weakness in the China business and intensifying competition in North America as reasons, and rather than structural growth they present “selective buying, with a preference one step below ODM”를.
LG Household & Health Care(051900): a “recovery phase” before a rerating
LG Household & Health Care is a representative stock whose rerating was delayed throughout the 2020s due to sluggish duty-free and China businesses.
2026As the year has progressed, some houses have raised their target prices from 24 million won to 28million won and 30million won, etc. to reflect upward revisions to earnings estimates, but investment opinions still largely remain in a HOLD (neutral) stance.
-
Looking at the news, expressions such as target prices of 24million won, 28million won, and 30million won, along with “raise earnings expectations but a cautious approach is needed” and “the road ahead is still rough”이 keep recurring.
-
In other words, there is short-term upside, but it is closer to a recovery story that requires more “risk and time” than ODM or Silicon Two.
11. 2026K-Beauty Investment Strategy Summary
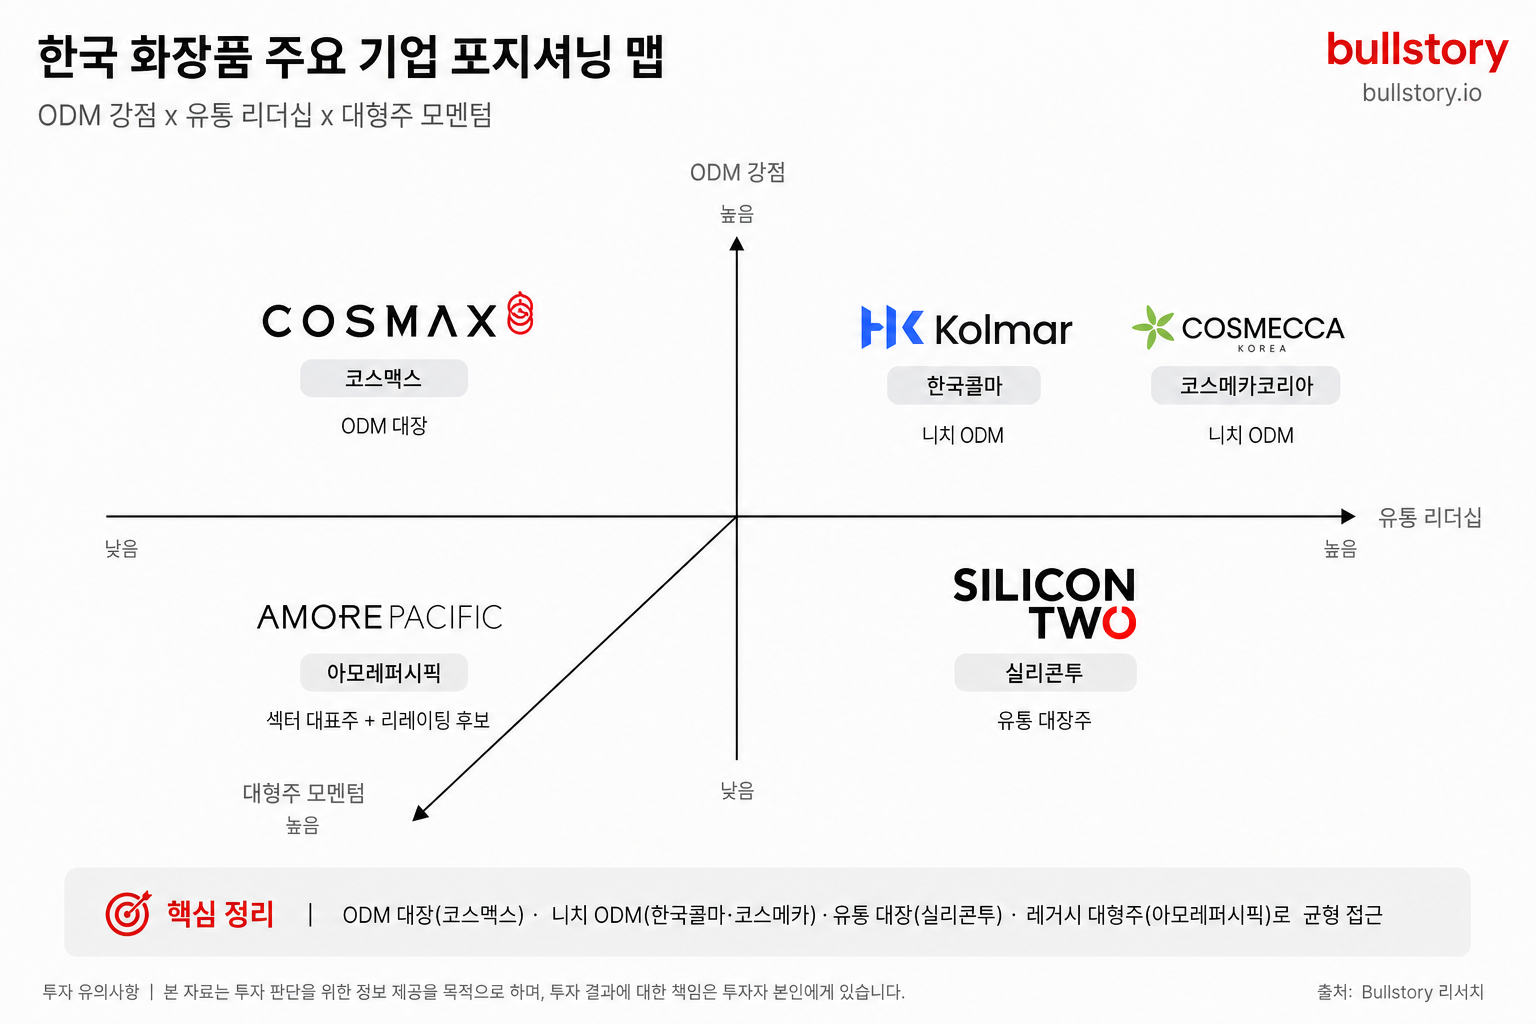
1) The core theme still remains “ODM + distribution + selective large caps”
-
Cosmax: the ODM leader + industry beta of this cycle. It is positioned to benefit simultaneously from the expansion of indie brands, strong exports to the United States and Europe, and improved profitability at overseas subsidiaries.
-
Kolmar Korea·Cosmecca Korea: in sun care and derma, 2stocks that provide medium- to long-term leverage in the niche of spillover effects from sun ODM.
-
Silicon Two: in the era of 1trillion won in sales, a distribution blue-chip that is receiving buy, high target price, and top pick within the sector from many brokerages.
-
Amorepacific: among legacy large caps, together with COSRX momentum, a stock that can be seen as a 85sector flagship plus re-rating candidate".
2) Trading vs medium- to long-term
-
If you are trading short term, a strategy that uses the volatility of Silicon Two and Cosmax, which have strong earnings surprise potential and news momentum, is effective.
-
For the medium- to long-term (3~5year view),
-
A portfolio structured to bet evenly across the entire value chain — Cosmax + Kolmar Korea/ Cosmecca + Silicon Two + Amorepacific (small weight) — is rational from a risk-diversification perspective.
3) Risks that must be checked
-
Protectionism and tariffs: If U.S. and European trade policies and regulations tighten, pressure may build on the margins of the entire K-beauty sector.
-
Country-specific certification and regulations (such as CPNP): If regulations tighten in Europe and Japan, barriers to entry for indie brands may rise, and the cost burden on ODM and distributors may increase.
-
China and duty-free recovery pace: a key variable in the re-rating of large brands (Amore and LG Household & Health Care).
-
Intensifying competition: competition in Europe and the United States with local brands and global major cosmetics companies, as well as the proliferation of K-beauty distribution platforms, may affect the margins and market share of distribution stocks such as Siliconto.
12. Practical buy-timing strategy for the K-beauty sector
1. Confirm the announcement of preliminary export data from the Korea Customs Service (on the 11day, 21day of each month)
The most powerful and immediate leading indicator that determines the direction of cosmetics stocks is the Korea Customs Service's daily import and export statistics. If the year-over-year (YoY) growth trend in cosmetics export amounts to the United States, Europe, and Japan is confirmed in the preliminary figures released on the 10day and the 11day each month, institutional and foreign buying flows come in strongly.**21.
- Strategy point: 2026year 4month, when cosmetics exports 13billion 7,400ten thousand dollars and the stock rally hit as it set a new all-time high, as if you mark the data release date on the calendar and use the period 2~3days before and after the release as the standard timing for short-term trading entries or adding to positions.
2. The overlap between major e-commerce events and earnings season (6late month ~ 7early month)
The share prices of indie brands and companies with global distribution networks (such as Siliconto) see expectations peak before and after major shopping events. In particular, the world’s largest discount sale event held in 7month 0;x;'Amazon Prime Day'ĦxB; K-beauty companies’ 3quarterly results are a decisive barometer.
- Strategy point: 2026year 6mid-month, from the current point in 7through early month is a favorable window for front-running purchases. This is because news of strong Prime Day sales results is reported, and then 8mid-month 2quarterly earnings releases (earnings season)�xAC; approaching tends to keep lifting stock prices on expectations for results.
3. Technical pullback within a structural rally (short-term profit-taking zone)
Leading sectors never rise in a straight line. K-beauty flagship stocks go through periodic price corrections due to institutional portfolio rebalancing or short-term profit-taking after a sharp uptrend in the first half of the year.
- Strategic point: The industry’s fundamentals, driven by export growth, are solid, but when the stock price drops sharply in the short term simply because of overall market supply-demand instability, 60or when it corrects down to key moving averages such as the first support line, it becomes the best staggered buying point for medium- to long-term investors. The current range, where the stock is taking a breather after part of its rise from the year’s high, is a good example.
In summary, 2026year 6as of month, K-beauty has completely reshaped its fundamentals into a structure of “indie brands → large domestic ODM and distribution companies → global consumers”, 77and, from the perspective of upside in the share price, the most natural setup is a strategy that centers on Cosmax and Silicontwo and combines Kolmar Korea, Cosmecca Korea, and Amorepacific.
Frequently asked questions
What is the reason K-beauty succeeded?
The key is distribution diversification and an ODM-centered production structure. Market growth was driven by the combination of export growth to the United States, Europe, and Japan, short-form marketing by indie brands, and production support from Korean ODMs.
Who is the leading player in the Korean cosmetics ODM 1space?
In the ODM segment, Cosmax is being presented as the global 1leader and as the sector’s top pick in reports from multiple brokerages.
What is a promising strategy when investing in K-beauty?
It is a pick-and-shovel strategy. To avoid the risks of indie brands, the key is to invest around OEM/ODM and global distribution platforms.
Who are the beneficiaries of indie brand growth?
Large ODM firms and cross-border distribution platforms. This is because when indie brands focus on planning and marketing, these firms handle production and distribution.
What impact has China’s sluggish exports had on K-beauty?
Although dependence on China has decreased, rising exports to North America, Europe, and Japan are offsetting that. Channel diversification is cushioning the losses.