Unlisted 100% holder, tax implications of the timing of stock gifts
60Mr. A, who has operated an unlisted corporation for years, applied for tax consultation over the timing of gifting his unlisted corporate stake 30% and listed shares he owns. BDO Sunghyun Accounting Corporation explained that, in principle, the value of gifted property is assessed at the market price as of the gift date, and that if market-price calculation is difficult, the supplementary valuation method prescribed by law is applied.100:
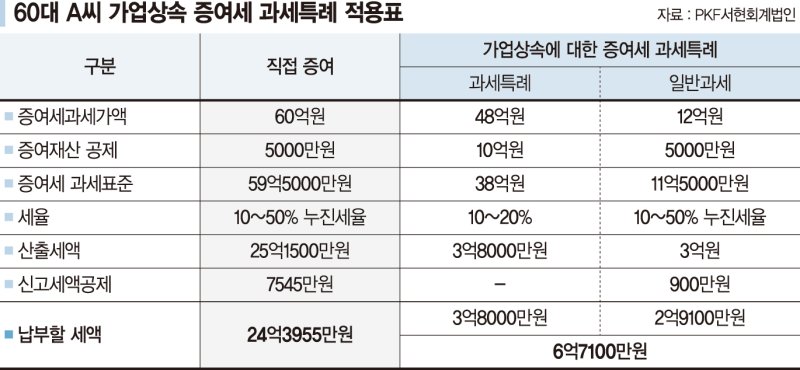
60Mr. A has operated an unlisted corporation for years. He said he holds the corporation’s shares 30% and listed shares that he bought and accumulated personally.100:
Mr. A applied for a consultation, saying he had heard that the tax differs depending on when shares are gifted and asking about the specific calculation method. 12On the day of the inquiry, BDO Sunghyun Accounting Corporation responded to the case.
BDO Sunghyun Accounting Corporation explained that the value of gifted property is, in principle, assessed at the market price as of the gift date, regardless of whether it is listed. It added that if the market price is difficult to determine, the supplementary valuation method prescribed by law is applied.
Listed stocks are valued based on the market price on the gift date, which is the valuation date, because a price is formed on the exchange. By contrast, unlisted stocks have no publicly available market price, so their value is determined using a supplementary valuation method, it explained.
BDO said that whether the market price can be confirmed is what creates the difference in valuation methods between listed and unlisted stocks. The article did not present any specific tax-saving measures or formulae for each case.
Sources: 파이낸셜뉴스 증권
Bullstory synthesized this report from the linked sources. AI may have assisted the writing process. Check the original reports for factual confirmation.